Table of Contents
The Complete Guide to India Statutory Deduction Accuracy and Filing Compliance
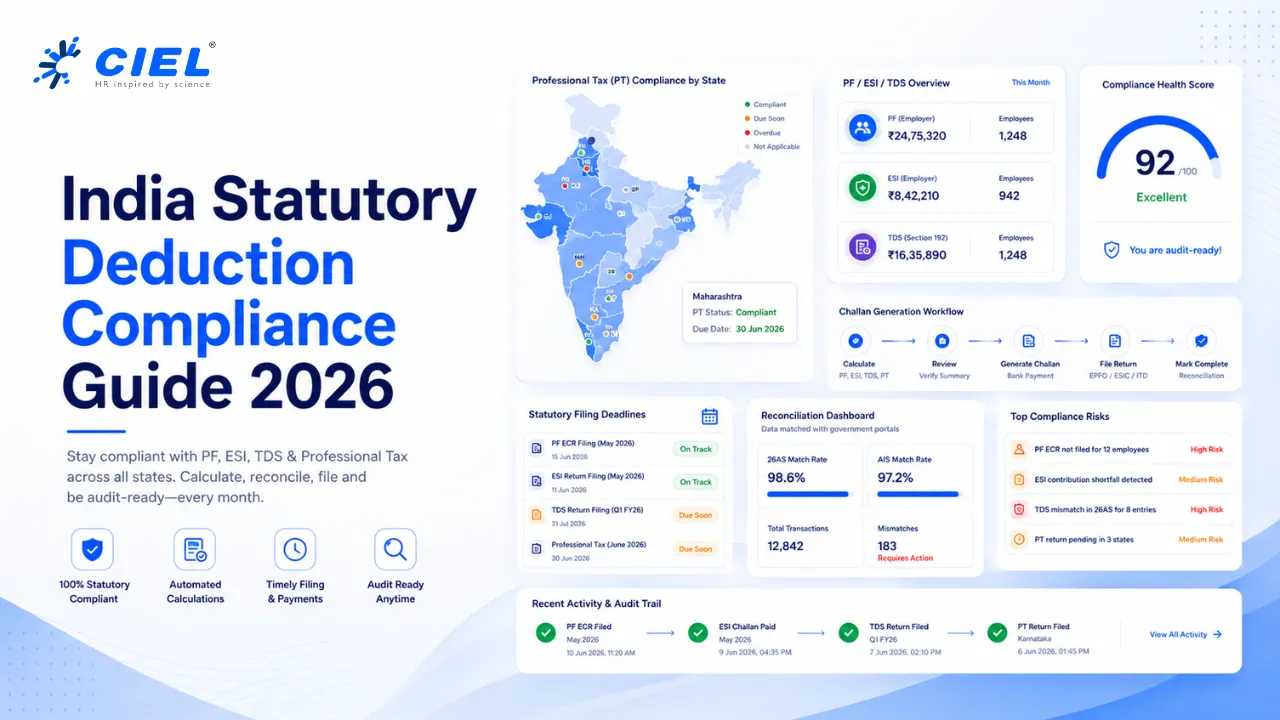
Ensuring India statutory deduction accuracy and filing compliance requires aligning internal payroll calculations with government mandates for TDS, PF, PT, and ESI. Automated compliance platforms ingest raw attendance data, apply state-specific regulatory rules, and generate formatted challans for direct portal submission. This mechanism eliminates manual reconciliation errors, prevents penalty accruals, and ensures organizational audit readiness across distributed workforces.
Why Is Managing Indian Statutory Deductions So Complex?
Statutory compliance management involves organizing a web of central and state-level regulations, including Provident Fund (PF), Employee State Insurance (ESI), and Tax Deducted at Source (TDS). This complexity creates a high-risk environment where a single miscalculation leads to compounding financial penalties. Organizations face continuous exposure when tracking multi-state regulations without centralized oversight.
Most organizations process payroll assuming their spreadsheet formulas accurately reflect current labor laws. The salaries reach employee bank accounts, and the cycle appears successful. The operational reality is much more fragmented. Deducting the right amount for taxes and social security is only half the battle; depositing it under the correct administrative heads and filing the corresponding returns on time dictates true compliance.
Where Do Traditional Payroll Compliance Methods Break Down?
Traditional payroll compliance methods isolate deduction calculations from the actual filing workflows, requiring teams to manually port data into government-mandated utility formats. This disconnection introduces data entry errors and delays the generation of statutory challans. The resulting lag prevents timely corrections before filing deadlines expire.
These methods break down entirely during the reconciliation phase between internal ledgers and government portals. Finance teams attempt to perform a reconciliation of company payroll records with the government’s 26AS and AIS portals at the end of the quarter, only to discover misaligned tax credits. When data is isolated in static files, identifying which specific employee record caused a bulk upload failure becomes a forensic accounting exercise.
How Do Automated Compliance Platforms Automate Statutory Filings?
Automated compliance platforms connect internal HRIS attendance modules to a central rules engine where organizations process multi-state payroll deductions via tax calculators. This integration reduces penalty risks by 90-100% annually. The mechanism directly formats the output for immediate portal submission.
These systems incorporate the essential features of a payroll system for automating TDS, PF, and ESI calculations accurately by continuously updating their internal tax logic against legislative changes. When payroll is finalized, the platform generates an encrypted payload containing the exact challan details required for the government gateways. This eliminates the manual extraction process and establishes a verifiable audit trail for every financial transaction.
How Does Passive Monitoring Compare to Active Compliance in Practice?
A regional finance team at a distributed IT staffing firm sits in a windowless conference room on the 14th of the month, surrounded by printed ledgers and multi-state professional tax spreadsheets. They have 400 remote employees spread across Karnataka, Maharashtra, and Tamil Nadu. The payroll was disbursed on the 1st, but the filing deadline for PF and PT is tomorrow. The team realizes that 15 employees transferred locations mid-month, meaning their professional tax deductions were calculated under the wrong state slabs.
The raw data captured the location changes, but the static payroll system did not automatically adjust the deduction logic. No one knew about the discrepancy until the finance manager attempted to generate the state-specific challans. That is passive monitoring working exactly as designed. The record exists. The response did not, leaving the company exposed to immediate non-compliance penalties and a frantic manual recalculation process overnight.
The same scene under an active compliance platform plays out differently. On the 20th of the previous month, when the HR portal registers the location transfers, the system pushes an automated webhook alert to the payroll dashboard. Not a generic warning, but a specific recalculation prompt: 15 records updated, PT slabs adjusted from Maharashtra to Karnataka, net pay variance flagged. The manager approves the updated ledger before the payroll run even begins. No one scrambled to fix the challan. The platform aligned the deductions before the error occurred.
What Is the Difference Between Automated and Manual Compliance Processing?
Automated compliance processing maps raw payroll data directly to statutory filing APIs, generating ready-to-upload challans without human intervention. This integration cuts reconciliation time by up to 80% compared to manual spreadsheet tracking. Organizations achieve immediate audit readiness rather than relying on retroactive corrections.
| Feature | Automated Compliance Processing | Traditional Payroll Processing |
|---|---|---|
| Tax Slab Updates | Real-time algorithmic updates via cloud | Manual legislative tracking and formula edits |
| Portal Reconciliation | Direct API matching with 26AS/AIS portals | Manual line-by-line verification |
| Multi-State Compliance | Dynamic location-based calculation | Static regional spreadsheets |
| Audit Trail | Immutable digital transaction logs | Fragmented email and file histories |
What Is the Process for Preparing for a Statutory Compliance Audit in India?
Statutory compliance audit preparation requires systematically validating deduction accuracy, filing timelines, and employee documentation against government standards. This centralized validation prevents penalty assessments during departmental inspections. Structured preparation ensures every deducted rupee matches the corresponding portal deposit.
To ensure readiness, evaluate your process using this compliance validation threshold logic:
- Employee Onboarding Documentation: IF PAN and Aadhaar linkage status is unverified for >5% of the workforce, THEN flag as HIGH RISK. Action: Suspend payroll processing for affected individuals until documentation is collected.
- TDS Reconciliation: Deviation rate >1% between internal ledgers and 26AS/AIS portals = FAIL. Action: Initiate immediate manual review of the previous quarter’s challans.
- PF/ESI Remittance: IF deposit date > 15th of the subsequent month for any cycle, THEN automatic penalty accrual applies. Action: Calculate and pay interest proactively to avoid compounding fines.
- Multi-State PT Compliance: Registration missing in >0 operating states = FAIL. Action: Apply for local PT enrollment before processing regional payroll.
What Are the Trade-offs of Adopting Automated Compliance Platforms?
Automated compliance platforms require standardized input data to function effectively, meaning organizations with highly unstructured HR records face steep initial deployment curves. This dependency forces companies to clean their legacy data before realizing any efficiency gains. The approach is most effective when basic onboarding documentation is already digitized.
- Not suitable when the organization lacks a centralized HRIS to feed attendance and leave data accurately.
- Trade-off: High initial setup time required to map existing employee structures and historical ledgers to the new rules engine.
- Not suitable for companies that rely heavily on undocumented cash disbursements or informal wage agreements that bypass digital tracking.
What Are the Next Steps for Improving Deduction Accuracy?
Improving deduction accuracy starts with auditing current workflows to identify disconnection points between payroll calculation and portal filing. This evaluation highlights exactly where manual data entry introduces risk. Teams can then explore integrated platforms that bridge these operational gaps.
To learn how to manage multi-state professional tax compliance for a remote workforce in India without scaling your headcount, begin by reviewing your current error rates. Map out how long your team spends on manual reconciliation, and explore automated solutions tailored to your operational scale.
Frequently Asked Questions
What are the technical prerequisites for integrating a new payroll compliance platform?
Organizations must consolidate their employee master data, including PAN, Aadhaar, and Universal Account Numbers (UAN), into a standardized database. The platform requires a stable API integration with your existing HRIS to automatically ingest daily attendance and leave metrics before the payroll cutoff.
What is the typical ROI timeframe for implementing automated statutory filing systems?
Companies achieve a positive return on investment within 6 to 9 months. This is driven by the immediate elimination of late filing penalties, reduced reliance on external tax consultants, and a 70% decrease in manual reconciliation hours spent by internal finance teams.
How does the system automate TDS, PF, and ESI calculations?
The rules engine applies current legislative tax slabs directly to the gross salary data ingested from the HRIS. It separates taxable components from exemptions, calculates the exact deduction, and formats the output into the specific XML or JSON payload required by the government portals.
What are the most common mistakes to avoid in Indian payroll statutory compliance?
The most frequent errors include missing the 15th-of-the-month deadline for PF and ESI remittances, failing to update professional tax deductions when remote employees relocate to different states, and filing mismatched TDS challans due to incorrect or unlinked PAN data.
Can you provide a monthly checklist for ensuring statutory deduction and filing compliance in India?
A standard monthly workflow involves locking attendance data by the 25th, validating onboarding documents for new hires, running the automated tax calculator, generating challans by the 10th, and completing all portal submissions prior to the 15th to prevent late fees.
What documents and information are mandatory to collect during employee onboarding for statutory compliance?
Employers must collect the employee’s PAN card, Aadhaar card, previous employer’s UAN for provident fund continuation, and a completed Form 11. Gathering these documents immediately ensures accurate tax slab application and correct portal mapping during the very first payroll cycle.
